HomeLandlord InsuranceProperty Developer Insurance

Property DeveloperInsurance

Property Developer Insurance

Cover for works in progress, site risks and completed units, built for new builds, conversions and renovation projects.

Cover for works in progress, site risks and completed units, built for new builds, conversions and renovation projects.

Contract works
Site & passers-by
Unoccupied once built
Compare from 20+ Trusted Insurers

Cover for property developers across the UK

Speak to a specialist 0330 027 0996

Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL
Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL

What is property developer insurance?

Property developer insurance covers a building project from site acquisition through to sale or letting. It combines contract works cover for the build itself, public liability, employers’ liability, and cover for the property once complete.

Development is a different risk to owning finished property, an incomplete building is more exposed to fire, theft and weather, and standard property policies won’t respond.

The right developer cover depends on:

New build, conversion or renovation
Contract value and build period
Whether the property is occupied
Plant and materials on site
Whether you sell or retain units
Number of concurrent projects
A man getting into a car outside an office building

Is property developer insurance right for your project?

Is property developer insurance right for your project?

If you’re building, converting or renovating rather than simply owning finished property, this is the cover built for you, at any project scale.

If you’re building, converting or renovating rather than simply owning finished property, this is the cover built for you, at any project scale.

New Builds

Ground-up construction of houses, flats or commercial units.

Conversions

Changing a building’s use, such as offices or barns into residential.

Renovations

Major refurbishment of an existing structure, often while it stands empty.

Extensions

Adding to a property, where the existing structure also needs insuring.

Build-to-Rent

Developments you intend to retain and let once complete.

Multiple Sites

Developers running several projects at different stages at once.

What could put your development at risk?

What could put your development at risk?

Theft of materials and fire on part-built structures cause most development claims, with weather damage close behind on buildings not yet watertight.

Theft of materials and fire on part-built structures cause most development claims, with weather damage close behind on buildings not yet watertight.

Fire on a part-built structure, where there’s no completed fire separation and materials are often exposed.

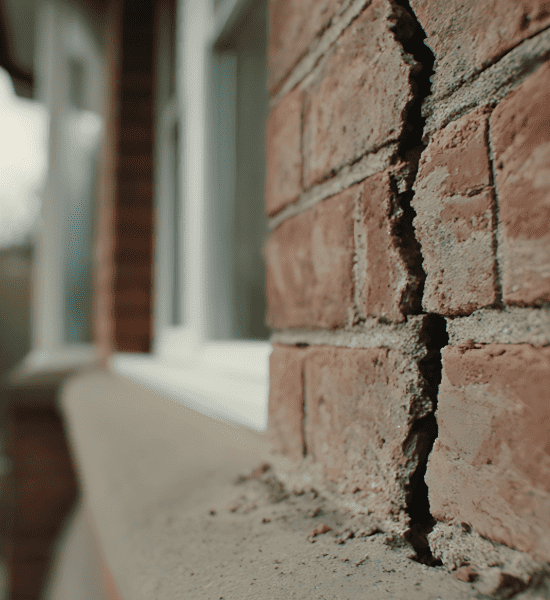
Close-up of a crack running down brickwork beside a window.

How could a claim affect your project?

How could a claim affect your project?

A single incident can destroy work you’ve already paid for and push back completion. Here are four common scenarios and the cover that responds.

A single incident can destroy work you’ve already paid for and push back completion. Here are four common scenarios and the cover that responds.

Fire

A fire destroys weeks of completed work before handover.

What cover may respond?

Contract Works

Escape of Water

Materials are stolen from site overnight before installation.

What cover may respond?

Contract Works + Plant

Storm Damage

Storm damage sets the programme back and delays completion.

What cover may respond?

Contract Works + Delay in Start-Up

Visitor Injury

A worker or visitor is injured on site.

What cover may respond?

Employers’ & Public Liability

A man getting into a car outside an office building

Who needs property developer insurance?

If you’re building, converting or renovating, standard property insurance won’t respond, and if you engage anyone on site, employers’ liability becomes a legal requirement.

This cover may be suitable for:

New build developers
Conversion specialists
Renovation and refurbishment developers
Build-to-rent developers
Developers running multiple sites
Self-builders and small developers

Starting on site soon?

Starting on site soon?

Contract works cover needs to be in place before work begins, and your lender will usually require it.

Contract works cover needs to be in place before work begins, and your lender will usually require it.

Aerial view of a cleared building plot among houses and gardens.

Cover built around your development

Cover built around your development

Most developers combine contract works cover for the build with public and employers’ liability, then add plant cover and unoccupied cover once units complete.

Most developers combine contract works cover for the build with public and employers’ liability, then add plant cover and unoccupied cover once units complete.

Contract Works

Contract Works

Covers the building work itself while in progress, including site materials and temporary structures.


Public Liability

Public Liability

Protection if a member of the public or a site visitor is injured, or their property is damaged.


Employers’ Liability

Employers’ Liability

A legal requirement once you engage anyone on site, including labour-only subcontractors.


Plant & Equipment

Plant & Equipment

Covers owned and hired-in plant, which you’re usually liable for under the hire agreement.


Unoccupied Cover

Unoccupied Cover

Protection for a completed but unsold or unlet unit, when standard cover restricts.


Legal Expenses

Legal Expenses

Legal protection for contract disputes with clients, contractors and suppliers.


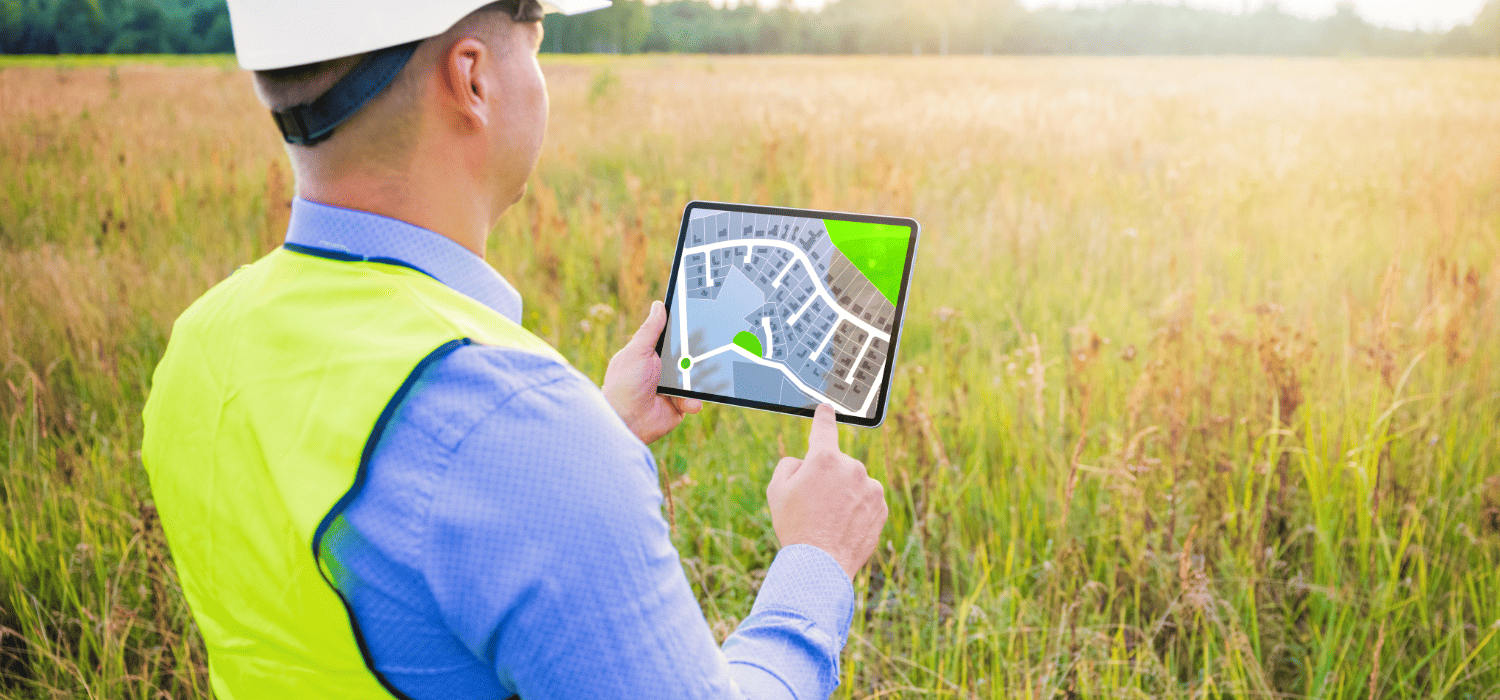
Surveyor in a hard hat and hi-vis holding a site plan on a tablet in a field.

Why choose us for property developer insurance?

We arrange cover that follows a project through every stage, from bare site to completed unit awaiting sale or letting.

Specialist development insurers
Experienced UK advisers
Single project or annual cover
Cover for new builds, conversions and renovations
Support for sites left empty overnight
Cover for multiple concurrent projects

How the quote process works

How the quote process works

Simple steps. Expert advice on the cover your project actually needs.

Simple steps. Expert advice on the cover your project actually needs.

1

Tell us about the project

What you’re building, the contract value and the timescale.

2

Set your sum insured

Cover should reflect the full reinstatement value of the works.

3

We compare specialist insurers

We search insurers who underwrite development risk.

4

Get covered before work starts

Receive your documents, usually the same day.

We're with you all the way

UK-based specialist advisers
Access to specialist insurers
No obligation, just expert help

Completed but not yet sold or let?

Completed but not yet sold or let?

A finished unit standing empty is treated differently to an occupied one, and most policies restrict cover once it’s unoccupied.

A finished unit standing empty is treated differently to an occupied one, and most policies restrict cover once it’s unoccupied.

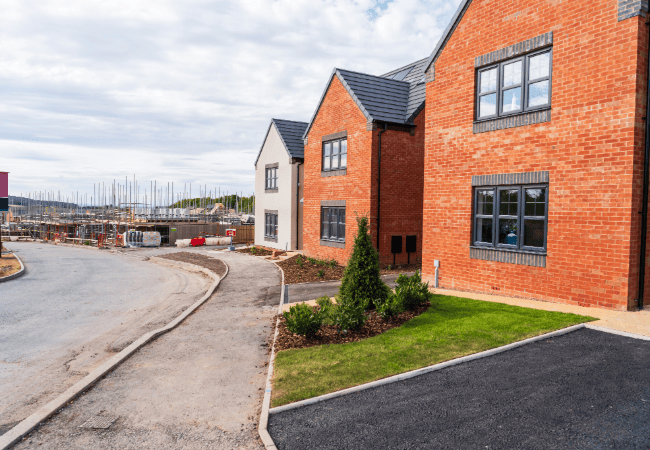
Newly built brick houses beside an unfinished road and construction site.

Trusted by thousands of businesses across the UK

Trusted by thousands of businesses across the UK

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

Property developer insurance guides

Property developer insurance guides

Practical advice on contract works, site risks and completed units.

Practical advice on contract works, site risks and completed units.

Does the Renters’ Rights Bill Change Your Landlord Insurance?

Does the Renters’ Rights Bill Change Your Landlord Insurance?

The Renters’ Rights Act introduces some of the biggest changes to England’s private rented sector in decades. From the removal of Section 21 ‘no fault’ evictions to changes in tenancy agreements and rent increases, landlords now face a different legal landscape than they did just a few years ago.

Read More
How to Reduce Your Landlord Insurance Premiums

How to Reduce Your Landlord Insurance Premiums

Landlord insurance is a vital cost for protecting your rental property, but that doesn’t mean you should overpay. This guide explains how to reasonably reduce your landlord insurance premiums while still protecting your investment.

Read More
Top Landlord Insurance Claims And How To Prevent Them

Top Landlord Insurance Claims And How To Prevent Them

Most landlord insurance claims follow familiar patterns. But the emerging pattern in 2025-26 is how often they happen and how much they cost. Rising repair prices and more extreme weather mean even routine claims are becoming more expensive.

Read More
Landlord Insurance UK: What Every Buy-to-Let Owner Needs to Know

Landlord Insurance UK: What Every Buy-to-Let Owner Needs to Know

Owning a buy-to-let property can offer a reliable income stream, but it also brings exposure to risks that standard home insurance may not cover. From accidental damage to liability claims and tenant-related losses, landlords face a unique set of challenges. Landlord insurance can provide tailored protection to help safeguard rental income, the property itself, and the landlord’s legal responsibilities.

Read More
Landlord Insurance Claims: What to Do When Tenants Cause Damage or Rent Goes Unpaid

Landlord Insurance Claims: What to Do When Tenants Cause Damage or Rent Goes Unpaid

Letting a property can bring consistent returns, but it can also come with unexpected challenges. From physical damage caused by tenants to rent arrears that disrupt income, landlords may face situations that require a carefully managed insurance claim.

Read More
Why Hidden Risks Can Cost Landlords Thousands

Why Hidden Risks Can Cost Landlords Thousands

Many landlords think they are covered because they hold a general business or property policy. But commercial property insurance is designed to address the real threats landlords face. Without it, one event can lead to huge losses.

Read More
Landlord Insurance Mistakes: 5 Things UK Property Owners Get Wrong

Landlord Insurance Mistakes: 5 Things UK Property Owners Get Wrong

When arranging residential landlord insurance in the UK, it can be easy to assume standard policies cover everything. However, there are several common mistakes property owners make when choosing or reviewing their level of cover. Overlooking these could leave landlords exposed to financial risks.

Read More
What Commercial Landlord Insurance Actually Covers: From Fires to Tenant Lawsuits

What Commercial Landlord Insurance Actually Covers: From Fires to Tenant Lawsuits

When owning a commercial property, arranging the right commercial landlord insurance can help protect both the building and your business interests. While many property owners understand the basics, not everyone knows exactly what this type of cover includes. From fire damage to legal actions linked to tenants, commercial landlord insurance could offer vital financial protection.

Read More
Do You Need Landlord Insurance If Your Tenant Already Has Business Insurance?

Do You Need Landlord Insurance If Your Tenant Already Has Business Insurance?

When letting out a commercial property, some landlords assume that if a tenant holds business insurance, it covers all risks. In reality, commercial landlord insurance and tenant business insurance serve different purposes. Knowing where the responsibilities lie helps property owners avoid gaps in financial protection.

Read More

Property developer insurance FAQs

Property developer insurance FAQs

Straight answers on contract works, site risks and completed units.

Straight answers on contract works, site risks and completed units.

It covers a building project from site through to sale or letting, combining contract works cover for the build itself, public and employers’ liability, and cover for the property once complete.

Still have questions?

Our advisers are here to help you find the right solution.