




What is trustee indemnity insurance?
What it covers, what it excludes, and who pays for it.

Public liability, trustee indemnity and volunteer cover built for charities, community groups and not-for-profits.
Public liability, trustee indemnity and volunteer cover built for charities, community groups and not-for-profits.
 Volunteer coverTrustee indemnityLiability at events
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
Charity insurance is a combination of covers built around running a not-for-profit, public liability for events and activities, employers’ liability for staff and volunteers, and trustee indemnity to protect the people who run it.
Trustees can be held personally liable for decisions made on the charity’s behalf. The Charities Act 2011 expressly allows charity funds to be used to buy insurance protecting them.
Charity insurance can include:
 Public liabilityEmployers’ liabilityTrustee indemnityBuildings and contentsFundraising events coverProfessional indemnity
Employers’ liability is legally required if your charity employs anyone. Everything else depends on what your charity does, who it works with and whether it owns property.
You should seriously consider cover if you:
Employ staff or paid workersRely on volunteersRun events or fundraising activitiesOwn or rent premisesHold personal data about beneficiariesHave a board of trusteesYes. Section 189 of the Charities Act 2011 expressly allows trustees to buy insurance out of charity funds to indemnify themselves against personal liability for breach of trust or breach of duty.
Charity Commission guidance CC49 confirms charitable funds may be used this way, an earlier reluctance no longer applies.
Trustee indemnity is worth considering if your charity:
Is unincorporatedHolds significant funds or assetsEmploys staffStruggles to recruit trusteesDelivers regulated or funded services
Does your charity’s structure affect trustee liability?
Does your charity’s structure affect trustee liability?
It matters a great deal. Incorporated charities have their own legal identity, so liabilities usually sit with the organisation. In unincorporated charities, trustees can be personally liable.
It matters a great deal. Incorporated charities have their own legal identity, so liabilities usually sit with the organisation. In unincorporated charities, trustees can be personally liable.
| Charity structure | Who carries liability | What to know |
|---|---|---|
Unincorporated association | Trustees personally, without limit | Trustees can be liable for debts the charity can’t meet |
Charitable trust | Trustees personally, without limit | Personal assets may be exposed if funds run short |
Charitable company (CIO) | The organisation, in most cases | Incorporation gives trustees far greater protection |
Company limited by guarantee | The organisation, in most cases | Directors still owe duties and can be pursued for breaches |

Top Tip
Trustee indemnity won’t cover everything, it excludes fraud, dishonesty and reckless conduct, and it doesn’t replace acting in good faith and within your governing document.
What could go wrong for a charity?
What could go wrong for a charity?
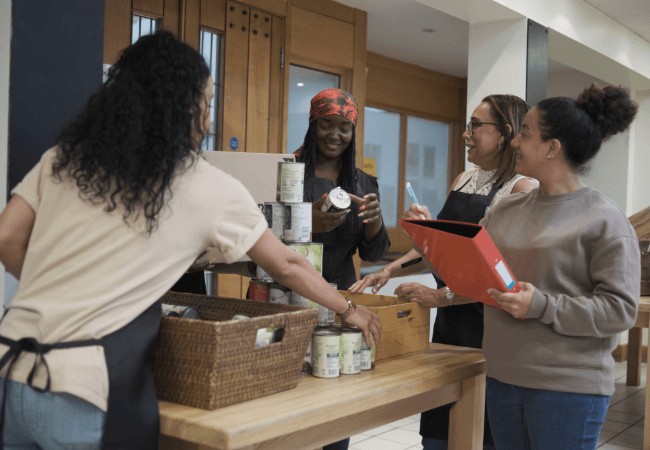
Most charity claims come from someone injured at an event, a volunteer hurt while helping, a trustee decision being challenged, or a breach involving beneficiary data.
Most charity claims come from someone injured at an event, a volunteer hurt while helping, a trustee decision being challenged, or a breach involving beneficiary data.
Volunteers count as employees for insurance purposes, even though they’re unpaid.
Once you’re covered we’ll send your documents the same day. Funders, local authorities and venues routinely ask for proof before releasing grants or confirming bookings.
If your charity employs anyone, your employers’ liability certificate must be displayed where staff can see it.
Your certificate typically shows:
Your charity’s nameYour insurer’s namePolicy numberPolicy start and renewal datesAny specific conditions
Cover often bought alongside charity insurance
Cover often bought alongside charity insurance
Most charities start with public and employers’ liability, then add trustee indemnity to protect the board and cover for premises, events or data.
Most charities start with public and employers’ liability, then add trustee indemnity to protect the board and cover for premises, events or data.
 Recommended
Employers’ Liability
Legally required if you employ anyone, and volunteers usually count too.
 Recommended
Trustee Indemnity
Protects trustees personally against claims for breach of trust or breach of duty.
 Optional
Public Liability
Covers injury or damage claims from events, activities and members of the public.
 Optional
Buildings & Contents
Protects charity premises, community buildings, equipment and donated goods.
 Optional
Cyber Insurance
Helps with the costs of a breach involving beneficiary or donor data.
 Popular
Commercial Combined
Bundle public liability with your other covers into one policy and one renewal date.
There’s no fixed price. What your charity does matters most, a grant-making trust and a charity running youth activities carry very different risks.

What your charity does
Working with children, vulnerable adults or running events raises your risk profile.
Claims history
A clean claims record helps keep premiums down at renewal.
Number of staff and volunteers
Volunteers usually count towards your employers’ liability exposure.

Premises and assets
Owning or renting a community building adds buildings and contents cover.

Your charity’s structure
Unincorporated charities carry more trustee exposure than CIOs or companies.
Events and activities
Fundraising events, trips and public activities affect your public liability needs.
How to get charity insurance
How to get charity insurance
Getting charity insurance takes four steps: tell us about your charity, choose your covers, compare specialist insurers, then get your documents, often the same day.
Getting charity insurance takes four steps: tell us about your charity, choose your covers, compare specialist insurers, then get your documents, often the same day.

Tell us about your charity
What you do, your structure and whether you have staff or volunteers.

Choose your covers
Public liability, employers’ liability, trustee indemnity and any extras.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and get your documents
Receive your certificates, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Charity insurance guides
Charity insurance guides
Practical advice on trustee liability, volunteers and staying protected.
Practical advice on trustee liability, volunteers and staying protected.
Charity insurance FAQs
Charity insurance FAQs
Straight answers on trustee liability, volunteers and cover.
Straight answers on trustee liability, volunteers and cover.
Employers’ liability is legally required if you have staff or volunteers. Most charities add public liability for events and activities, trustee indemnity to protect the board, and cover for premises and data.
Still have questions?
Our advisers are here to help you find the right solution.

