HomeLandlord InsuranceBuy to Let Insurance

Buy-to-LetInsurance

Buy-to-Let Insurance

Buildings, contents and liability cover that meets what your buy-to-let mortgage lender requires.

Buildings, contents and liability cover that meets what your buy-to-let mortgage lender requires.

Lender rebuild cost
Rent while mortgaged
Landlord contents
Compare from 20+ Trusted Insurers

Cover for buy-to-let landlords across the UK

Speak to a specialist 0330 027 0996

Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL
Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL

What is buy-to-let insurance?

Buy-to-let insurance is landlord cover for a property bought as an investment and let to tenants. It combines buildings cover for the structure, landlord contents, and property owners’ liability, and is usually a condition of your mortgage.

Almost every buy-to-let lender requires buildings cover set to the full rebuild cost before releasing funds, and will expect it maintained for the life of the loan.

The right buy-to-let cover depends on:

Your lender’s requirements
Freehold or leasehold
Tenant type and tenancy
Rebuild cost of the property
Annual rental income
Number of properties mortgaged
A man getting into a car outside an office building

Is buy-to-let insurance right for your property?

Is buy-to-let insurance right for your property?

If you have a mortgage on a property you let, this is the cover built for you, whether it’s your first buy-to-let or one of several.

If you have a mortgage on a property you let, this is the cover built for you, whether it’s your first buy-to-let or one of several.

First Buy-to-Let

A single mortgaged property let to private tenants on an AST.

Leasehold Flats

Where the freeholder insures the block but your lender still wants proof of cover.

Furnished Lets

Properties let with white goods, carpets and furnishings you own.

Let-to-Buy

Where you let a former home after moving, often on a consent-to-let or BTL remortgage.

Limited Company BTL

For properties held in a personal name or a LTD company.

Buy-to-Let Portfolios

Landlords with several mortgaged properties under one policy.

What could put your buy-to-let at risk?

What could put your buy-to-let at risk?

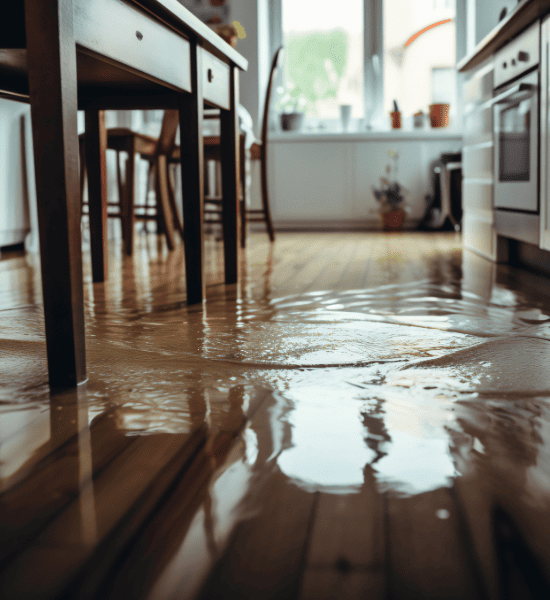
Fire and escape of water cause most buy-to-let claims, and both can leave a mortgaged property uninhabitable while repayments continue.

Fire and escape of water cause most buy-to-let claims, and both can leave a mortgaged property uninhabitable while repayments continue.

Damage to the structure, fixtures and fittings, the loss your lender’s buildings cover requirement exists to protect against.

Learn More
Flood water across a wooden kitchen floor, reflecting the units above.

How could a claim affect your property?

How could a claim affect your property?

A single incident can stop your rent while your mortgage still needs paying. Here are four common scenarios and the cover that responds to each.

A single incident can stop your rent while your mortgage still needs paying. Here are four common scenarios and the cover that responds to each.

Fire

A fire damages the property and your tenant has to move out.

What cover may respond?

Buildings + Loss of Rent

Escape of Water

A burst pipe damages the structure and the tenant’s belongings.

What cover may respond?

Buildings + Property Owners’ Liability

Storm Damage

Severe weather damages the roof and the property is uninhabitable.

What cover may respond?

Buildings + Loss of Rent

Visitor Injury

A tenant is injured by something at the property.

What cover may respond?

Property Owners’ Liability

A man getting into a car outside an office building

Who needs buy-to-let insurance?

If you have a buy-to-let mortgage, your lender will almost certainly require buildings cover at full rebuild cost as a condition of the loan, and will expect it kept in place for the life of the mortgage.

This cover may be suitable for:

First-time buy-to-let landlords
Owners remortgaging a rental property
Let-to-buy and consent-to-let landlords
Owners of furnished rentals
Landlords with multiple mortgaged properties
Owners letting leasehold flats

Lender asking for proof of cover?

Lender asking for proof of cover?

We can issue your certificate the same day, so a mortgage completion never waits on paperwork.

We can issue your certificate the same day, so a mortgage completion never waits on paperwork.

Certificate of insurance beside a pen, gavel and book on a wooden desk.

Cover built around your buy-to-let

Cover built around your buy-to-let

Most buy-to-let landlords start with the buildings cover their lender requires, then add liability, loss of rent and contents depending on how the property is let.

Most buy-to-let landlords start with the buildings cover their lender requires, then add liability, loss of rent and contents depending on how the property is let.

Buildings Insurance

Buildings Insurance

Protection for the structure, set to full rebuild cost, the cover your lender requires.


Property Owners’ Liability

Property Owners’ Liability

Protection if a tenant or visitor is injured at your property.


Loss of Rent

Loss of Rent

Helps replace rental income while the property is uninhabitable, and your mortgage still needs paying.


Landlord Contents

Landlord Contents

Cover for white goods, carpets, curtains and furnishings you provide.


Rent Guarantee

Rent Guarantee

Covers unpaid rent and legal costs if a tenant defaults, useful when a mortgage depends on that income.


Legal Expenses

Legal Expenses

Additional legal protection for tenancy disputes and possession proceedings.


Row of new build houses on a quiet residential street at sunset.

Why choose us for buy-to-let insurance?

We arrange cover that satisfies lender requirements, including the full rebuild cost figure your mortgage offer specifies.

Specialist buy-to-let insurers
Experienced UK advisers
Access to specialist insurers
Cover accepted by major BTL lenders
Properties held in a personal name or a limited company
Portfolio cover for multiple mortgaged properties

How the quote process works

How the quote process works

Simple steps. Expert advice on the cover your lender and your property need.

Simple steps. Expert advice on the cover your lender and your property need.

1

Tell us about your property

Type, location, tenancy and your lender’s requirements.

2

Set your rebuild cost

Cover should reflect rebuild cost, not the purchase price.

3

We compare specialist insurers

We search our panel of specialist landlord insurers.

4

Get covered before completion

Receive your documents for your lender, usually the same day.

We're with you all the way

UK-based specialist advisers
Access to specialist insurers
No obligation, just expert help

Letting the property to students or sharers?

Letting the property to students or sharers?

If three or more unrelated tenants share, the property may be an HMO, which changes both your licensing duties and your cover.

If three or more unrelated tenants share, the property may be an HMO, which changes both your licensing duties and your cover.

Three young housemates talking in a kitchen, one washing up at the sink.

Trusted by thousands of businesses across the UK

Trusted by thousands of businesses across the UK

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

Buy-to-let insurance guides

Buy-to-let insurance guides

Practical advice on lender requirements, rebuild costs and protecting rental income.

Practical advice on lender requirements, rebuild costs and protecting rental income.

Loss of Rent & Tenant Default Insurance: How to Protect Your Buy-to-Let Income

Loss of Rent & Tenant Default Insurance: How to Protect Your Buy-to-Let Income

Owning a rental property can provide a valuable source of income, but landlords can face financial risk if tenants fail to pay rent or if the property becomes temporarily uninhabitable. Loss of rent and tenant default insurance can offer protection to help safeguard rental income in these situations.

Read More
Buy-to-Let Insurance Checklist: 6 Must-Have Covers for Landlords

Buy-to-Let Insurance Checklist: 6 Must-Have Covers for Landlords

When renting out a property, it is important to understand exactly what buy-to-let insurance can cover. There is no single legal requirement for landlords to hold this type of policy in the UK. However, many mortgage lenders, letting agreements, and risk management strategies make it a recommended choice.

Read More
Is Buy-to-Let Insurance Legally Required in the UK? A Clear Answer

Is Buy-to-Let Insurance Legally Required in the UK? A Clear Answer

Letting a property can bring consistent returns, but it can also come with unexpected challenges. From physical damage caused by tenants to rent arrears that disrupt income, landlords may face situations that require a carefully managed insurance claim.

Read More
Why Buy-to-Let Insurance Pays for Itself

Why Buy-to-Let Insurance Pays for Itself

Owning a rental property can bring steady income, but it also comes with risks. Whether it is a single flat or a portfolio of houses, buy-to-let insurance is designed to provide financial protection against events that could affect your property, income, or liability.

Read More

Buy-to-let insurance FAQs

Buy-to-let insurance FAQs

Straight answers on lender requirements, cover and cost.

Straight answers on lender requirements, cover and cost.

Buy-to-let insurance is landlord cover for a property bought as an investment and let to tenants. It combines buildings cover for the structure, landlord contents, and property owners’ liability.

Still have questions?

Our advisers are here to help you find the right solution.