



Expert guides
Practical guides to business, vehicle and specialist insurance.

The one business insurance you can be fined for not having. Compulsory once you employ anyone, with a legal minimum of £5 million cover.
The one business insurance you can be fined for not having. Compulsory once you employ anyone, with a legal minimum of £5 million cover.
 Staff injury claims£5m statutory minimumLegal costs
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
Employers’ liability insurance covers the cost of compensation and legal fees if an employee is injured or becomes ill because of their work for you. It’s a legal requirement under the Employers’ Liability (Compulsory Insurance) Act 1969 for almost every UK employer, with a minimum indemnity limit of £5 million.
It doesn’t matter whether the employee is full-time, part-time, temporary or even a casual helper, if you control how they work, you likely need this cover.
Employers’ liability insurance can include:
 Compensation for workplace injuryCompensation for work-related illnessLegal defence costsCover for casual and temporary staffClaims going back many years
Which of these describes you?
Which of these describes you?
Employers’ liability rules apply differently depending on who works for you.
Employers’ liability rules apply differently depending on who works for you.
I employ staff
Full-time, part-time or casual, cover is a legal requirement.

I’m a sole trader with no staff
You’re not required to hold it, but check the rules if that changes.
I use subcontractors
Whether you need cover can depend on how much control you have over their work.
I run a limited company with no staff
A specific exemption may apply if you’re the sole director and shareholder.
I’m not sure if I need it
Tell us about your business and we’ll confirm what applies to you.
The Health and Safety Executive (HSE) enforces employers’ liability compliance and can inspect any workplace without warning. Trading without adequate cover, or without the minimum £5 million indemnity limit, is a criminal offence.
Fines apply per day, not per inspection, a business found without cover for a month can face tens of thousands of pounds in penalties before a single claim is even made.
The penalties can include:
Up to £2,500 per day without coverUp to £1,000 for not displaying your certificatePersonal liability for any claim that arisesLosing contracts that require proof of insuranceHSE inspection at any time, unannounced
Two specific exemptions exist under the 1969 Act. Almost everyone else needs cover.
You may be exempt if:
You’re a sole director who owns 50%+ of the companyYou only employ close family members as a sole traderYou have no employees at allYou only use genuinely self-employed contractorsYou employ people who work wholly outside the UKNot sure? We’ll check for youWhat could an employers’ liability claim cost you?
What could an employers’ liability claim cost you?
Employers’ liability claims range from a few thousand pounds for a minor injury to well over £1 million for a life-changing one, and HSE fines apply even before any claim is made.
Employers’ liability claims range from a few thousand pounds for a minor injury to well over £1 million for a life-changing one, and HSE fines apply even before any claim is made.
Minor injury
A staff member strains their back lifting stock and needs time off to recover.
Typical cost
£1,000-£10,000

Repetitive strain injury
An employee develops a work-related condition over months or years of the same task.
Typical cost
£5,000-£50,000

Serious injury
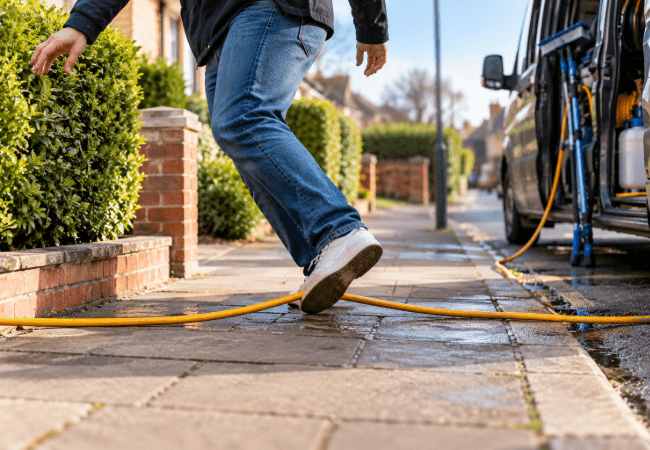
A fall, machinery accident or similar leaves an employee unable to work long-term.
Typical cost
£50,000-£1 million+
No Cover Applied
Even with no injury claim, trading without cover can be fined per day it continues.
Typical cost
Up to £2,500 a day
Once you’re covered, you’ll receive a certificate of insurance, and by law you must display it where your employees can see it, either printed or electronically. It’s also the document an HSE inspector will ask to see.
Keep old certificates. Claims can arise many years after the work took place, so you need proof of cover going back as far as your business does.
Your certificate must show:
Your business nameYour insurer’s namePolicy numberPolicy start and renewal datesEmployer Reference Number
There’s no fixed price for employers’ liability insurance. Your premium depends mainly on how many people you employ, the type of work they do, your total payroll, your industry and your claims history, office-based teams cost far less to cover than manual trades.
Number of employees
More staff generally means a higher premium, though the increase per head isn’t linear.
Claims history
A clean record helps keep premiums down at renewal.

Type of work
Office-based staff cost less to cover than those doing manual or higher-risk work.

Level of cover
Most insurers offer £10 million as standard even though £5 million is the legal minimum.

Payroll size
Many insurers price partly on your total wage bill, not just headcount.

Industry sector
Construction and manual trades are rated differently to offices and shops.
Public Liability
Covers claims if your business injures a customer or damages their property.
Professional Indemnity
Covers claims that your advice or service was negligent and caused a client loss.
Product Liability
Covers claims if a product you make, sell or supply causes harm.
Business Contents
Protects equipment, stock and fixtures against fire, theft and damage.
Business Interruption
Helps with lost income if an insured event stops you trading.
How to get employers’ liability insurance
How to get employers’ liability insurance
Simple steps. Cover usually in place the same day, with your certificate ready to display.
Simple steps. Cover usually in place the same day, with your certificate ready to display.

Tell us about your staff
How many employees, and the work they do.

Confirm your cover
£5 million minimum, or £10 million if you prefer.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and display your certificate
Receive your documents, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Employers’ liability guides
Employers’ liability guides
Practical advice on exemptions, minimum cover and claims for UK employers.
Practical advice on exemptions, minimum cover and claims for UK employers.
Expert guides
Resources
Tools
Employers’ liability insurance FAQs
Employers’ liability insurance FAQs
Straight answers on the legal minimum, exemptions, cost and claims.
Straight answers on the legal minimum, exemptions, cost and claims.
Employers’ liability insurance covers compensation and legal costs if an employee is injured or becomes ill because of their work for you. It’s a legal requirement under the Employers’ Liability (Compulsory Insurance) Act 1969 for almost every UK employer.
Still have questions?
Our advisers are here to help you find the right solution.