HomeBusiness InsuranceContract Works Insurance

Contract WorksInsurance

Contract Works Insurance

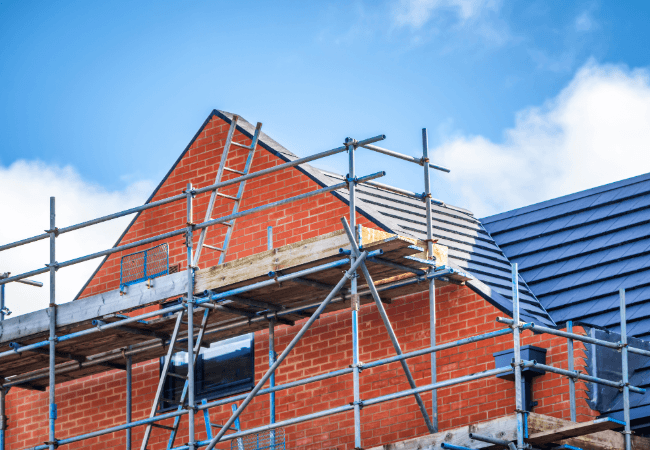
Cover for the work in progress itself, also known as contractors’ all risks, and the cover most JCT building contracts require you to hold.

Cover for the work in progress itself, also known as contractors’ all risks, and the cover most JCT building contracts require you to hold.

Work in progress
Site materials
Hired-in plant
Compare from 20+ Trusted Insurers

Cover for contractors across the UK

Speak to a specialist 0330 027 0996

Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL
Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL

What is contract works insurance?

Contract works insurance, also called contractors’ all risks, covers the building work itself while it’s in progress. If a half-built structure, site materials or a partly finished extension is damaged by fire, flood, storm or theft, this is the cover that pays to put it right.

Public liability covers harm to other people and their property. Contract works covers the job you’re actually building, which is why most contracts require both.

Contract works insurance can include:

Work in progress
Site materials
Plant and equipment
Temporary structures
Debris removal costs
Employee tools and effects
A man getting into a car outside an office building

Who needs contract works insurance?

It isn’t required by law, but most standard building contracts require it, so in practice it’s compulsory on the majority of construction projects.

You should seriously consider cover if you:

Build new structures or extensions
Carry out renovations or conversions
Work under a JCT or similar contract
Store materials on site
Hire in plant or scaffolding
Work on a client’s existing building

Contract asking for a joint names policy?

Contract asking for a joint names policy?

Joint names cover removes the insurer’s right to pursue the other party after a claim. We can arrange it in the names your contract specifies.

Joint names cover removes the insurer’s right to pursue the other party after a claim. We can arrange it in the names your contract specifies.

Certificate of insurance beside a pen, gavel and book on a wooden desk.

Is contract works insurance a legal requirement?

No, there’s no law requiring it. But JCT building contracts set out who must insure the works, and on most projects that obligation falls to the contractor, so your contract makes it compulsory even though legislation doesn’t.

Under JCT terms the cover usually has to run until the Practical Completion certificate is issued.

You’ll usually be required to hold it when you:

Sign a JCT building contract
Take on a main contractor role
Build under a client’s specification
Are asked for a joint names policy
Take on a domestic extension or renovation
A man getting into a car outside an office building

Which JCT clause applies to your project?

Which JCT clause applies to your project?

JCT contracts set out three options for insuring the works, and which one applies depends on whether you’re building new or working on an existing structure.

JCT contracts set out three options for insuring the works, and which one applies depends on whether you’re building new or working on an existing structure.

JCT optionWhen it appliesWho insures the works

Clause 22A / 6.7A

Erecting a new building

The contractor takes out and maintains all risks cover

Clause 22B / 6.7B

Erecting a new building

The employer takes out the cover instead

Clause 22C / 6.7C

Work to or extending an existing structure

The employer insures both the existing structure and the works

Joint names policy

Required under all three options

Written in the names of both contractor and client

Top Tip

A joint names policy matters more than it sounds: it removes the insurer’s right of subrogation, so they can’t pay one party then pursue the other to recover it. Check which clause your contract specifies before work starts.

What could go wrong on a contract?

What could go wrong on a contract?

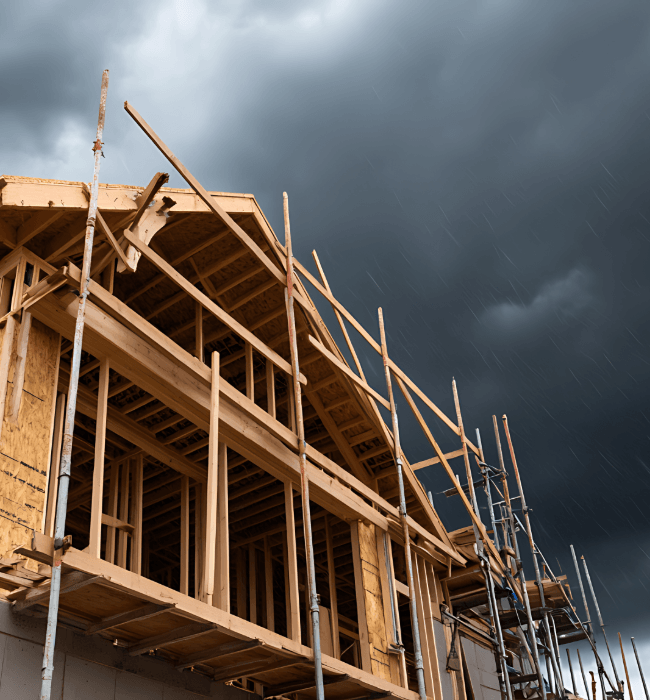
Most contract works claims come from fire, flood or storm damaging part-built work, theft of materials from site, or vandalism overnight.

Most contract works claims come from fire, flood or storm damaging part-built work, theft of materials from site, or vandalism overnight.

Weeks of completed work is destroyed before handover.

Timber-framed building under construction beneath dark storm clouds and rain.

What contract works insurance won’t cover

‘All risks’ is a misnomer. Standard contract works policies exclude a defined list of causes, and knowing them matters as much as knowing what’s included.

Faulty workmanship and defective design are the exclusions that catch contractors out most often.

Commonly excluded:

Wear and tear
Faulty workmanship
Defective design
Rust, mildew and deterioration
Loss or damage from war
A man getting into a car outside an office building

Cover often bought alongside contract works insurance

Cover often bought alongside contract works insurance

JCT contracts typically require public liability alongside contract works, one covers the job you’re building, the other covers harm to people and property around it.

JCT contracts typically require public liability alongside contract works, one covers the job you’re building, the other covers harm to people and property around it.

Public LiabilityRecommended

Public Liability

Required alongside contract works under most JCT contracts.


Employers’ LiabilityRecommended

Employers’ Liability

A legal requirement once you employ anyone on site, including labour-only subcontractors.


Plant & MachineryOptional

Plant & Machinery

Covers owned and hired-in plant, which you’re usually liable for under the hire agreement.


Tools & EquipmentOptional

Tools & Equipment

Covers the tools your team needs on site, including theft from a vehicle.


Business InterruptionOptional

Business Interruption

Helps with lost income and ongoing costs if an insured event stops you trading.


Commercial CombinedPopular

Commercial Combined

Bundle public liability with your other covers into one policy and one renewal date.


How much does contract works insurance cost?

There’s no fixed price. The contract value is the main driver, cover is usually written against the full reinstatement value of the works plus professional fees.

Contract value

Cover should reflect the full rebuild value of the works, not just your profit on the job.

Claims history

A clean claims record helps keep premiums down at renewal.

Type of project

Renovations to an existing structure carry different risk to a new build.

Site security

Fencing, lighting and alarms reduce theft and vandalism risk.

Contract length

Longer projects mean longer exposure to fire, theft and weather.

Single project or annual cover

Regular contractors often insure all projects under one annual policy.

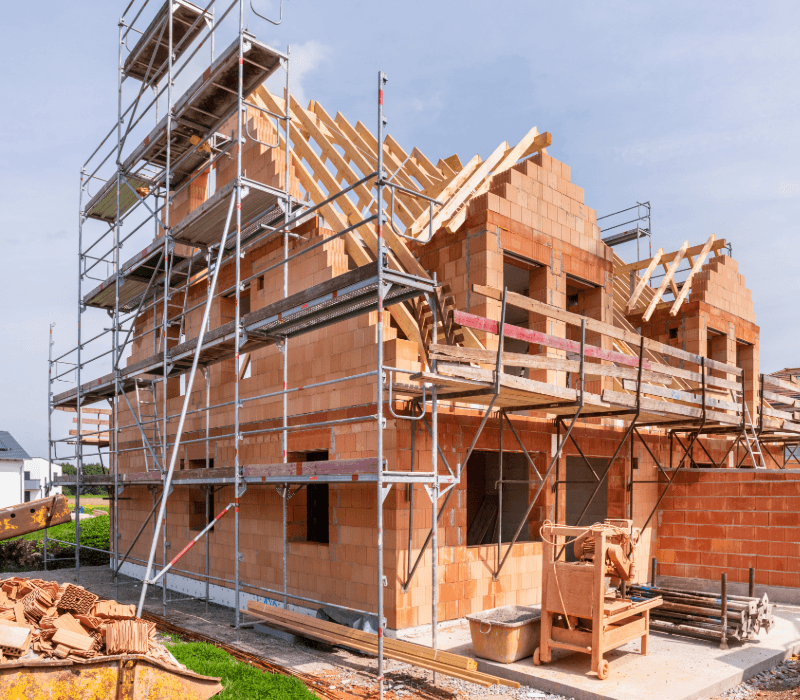
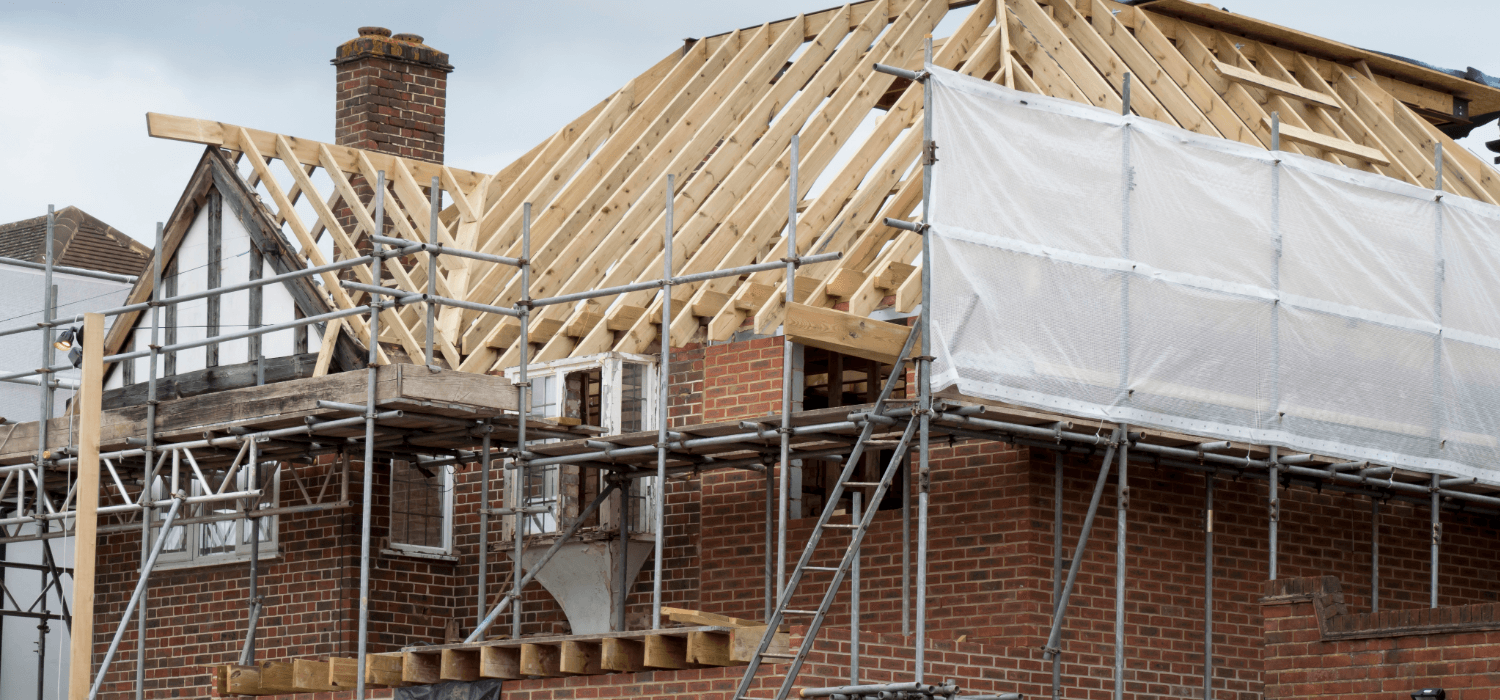
House renovation with new timber roof framing, scaffolding and protective sheeting.

Why use Insurance Revolution for contract works insurance?

We arrange cover that matches what your contract actually requires, including joint names policies where the contract specifies one.

Access to 20+ UK insurers
Joint names policies arranged
Help matching cover to your JCT clause
Experienced UK-based advisers
Single project or annual cover
Human support when you claim

How to get contract works insurance

How to get contract works insurance

Getting contract works insurance takes four steps: tell us about the project, set your sum insured, compare specialist insurers, then get covered before work starts.

Getting contract works insurance takes four steps: tell us about the project, set your sum insured, compare specialist insurers, then get covered before work starts.

1

Tell us about the project

What you’re building, the contract value and the timescale.

2

Set your sum insured

Cover should reflect the full reinstatement value of the works.

3

We compare specialist insurers

We search our panel of 20+ UK insurers.

4

Get covered before work starts

Receive your documents, usually the same day.

We’re with you all the way

UK-based specialist advisers
Access to specialist insurers
No obligation, just expert help

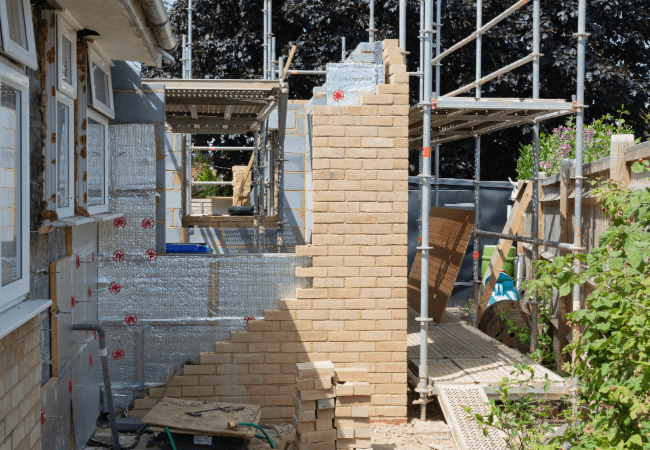
Working on a domestic extension?

Working on a domestic extension?

Renovations to an existing structure fall under a different JCT clause to new builds, and the cover usually sits with the homeowner.

Renovations to an existing structure fall under a different JCT clause to new builds, and the cover usually sits with the homeowner.

Partially built house extension with brick walls, exposed insulation and scaffolding.

Trusted by thousands of businesses across the UK

Trusted by thousands of businesses across the UK

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

Contract works insurance guides

Contract works insurance guides

Practical advice on JCT clauses, joint names cover and staying protected.

Practical advice on JCT clauses, joint names cover and staying protected.

Contract Works & Plant Cover for Builders: What You Need to Know

Contract Works & Plant Cover for Builders: What You Need to Know

Building projects often come with a wide range of risks, particularly when valuable materials, tools, and machinery are involved. Whether working on residential, commercial, or large-scale developments, builders may benefit from arranging tradesman insurance that specifically includes contract works and plant cover.

Read More
Contract Works Insurance Explained: Why Every Builder Should Have It

Contract Works Insurance Explained: Why Every Builder Should Have It

Building projects can involve multiple risks, from damage to works in progress to unexpected delays. For builders, contractors, and tradespeople, contract works insurance can offer essential protection for ongoing projects. Without suitable cover, rectifying unforeseen damage or loss could result in significant financial strain.

Read More
Builder Insurance Claims Guide: What to Do When Tools Are Stolen or Accidents Happen

Builder Insurance Claims Guide: What to Do When Tools Are Stolen or Accidents Happen

Builders face a variety of risks on-site, including theft of valuable tools and unexpected accidents that can disrupt projects and impact earnings. Knowing how to navigate the builder insurance claims process can be crucial when these situations occur.

Read More

Contract works insurance FAQs

Contract works insurance FAQs

Straight answers on JCT clauses, joint names cover and what’s excluded.

Straight answers on JCT clauses, joint names cover and what’s excluded.

Contract works insurance, also called contractors’ all risks, covers the building work itself while it’s in progress, including site materials and temporary structures, against fire, flood, storm, theft and vandalism.

Still have questions?

Our advisers are here to help you find the right solution.