HomeLandlord InsuranceLandlord Contents Insurance

Landlord ContentsInsurance

Landlord Contents Insurance

Cover for the furnishings, white goods and carpets you provide, not your tenant’s belongings.

Cover for the furnishings, white goods and carpets you provide, not your tenant’s belongings.

White goods & carpets
Curtains & fittings
Tenant damage add-on
Compare from 20+ Trusted Insurers

Cover for landlords across the UK

Speak to a specialist 0330 027 0996

Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL
Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL

What is landlord contents insurance?

Landlord contents insurance covers items you own inside a rental property, white goods, carpets, curtains, light fittings and any furniture you supply. Buildings insurance covers the structure; this covers what sits inside it.

It does not cover your tenant’s possessions. They need their own tenant contents policy, and it’s worth saying so in writing at the start of a tenancy.

The right landlord contents cover depends on:

Furnished, part-furnished or unfurnished
Value of items you provide
Whether carpets and curtains are included
Communal area furnishings
Accidental damage requirements
Number of properties let
A man getting into a car outside an office building

Is landlord contents insurance right for your property?

Is landlord contents insurance right for your property?

If you supply anything inside the property, even just carpets, curtains and a cooker, this is the cover that replaces it.

If you supply anything inside the property, even just carpets, curtains and a cooker, this is the cover that replaces it.

Fully Furnished Lets

Properties let with furniture, appliances and soft furnishings throughout.

Part-Furnished Lets

The most common arrangement, white goods, carpets and curtains but no furniture.

Unfurnished Lets

Even here, carpets, curtains and fitted appliances are usually yours to insure.

HMOs & Shared Houses

Shared kitchens and communal areas where furnishings take heavier use.

Student Lets

Higher turnover and heavier wear on furniture and appliances.

Serviced & Short Lets

Properties let fully equipped, where contents value is often highest.

What could put your contents at risk?

What could put your contents at risk?

Escape of water and theft cause most contents claims, and the damage to furnishings often costs more than the structural repair.

Escape of water and theft cause most contents claims, and the damage to furnishings often costs more than the structural repair.

Fire damaging furnishings, appliances and floor coverings throughout the property.

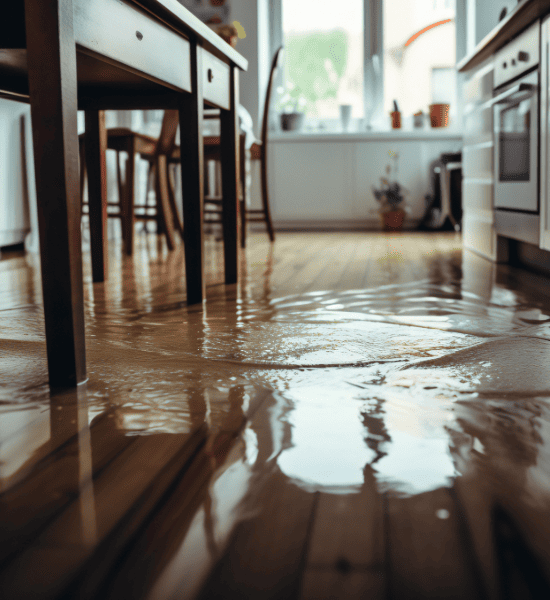
Flood water across a wooden kitchen floor, reflecting the units above.

How could a claim affect your property?

How could a claim affect your property?

Contents damage can make a property unlettable even when the building is sound. Here are four scenarios and the cover that responds.

Contents damage can make a property unlettable even when the building is sound. Here are four scenarios and the cover that responds.

Fire

A fire destroys the kitchen appliances and carpets you supplied.

What cover may respond?

Landlord Contents

Escape of Water

A leak soaks carpets and ruins furniture on the floor below.

What cover may respond?

Landlord Contents + Buildings

Storm Damage

White goods are stolen from the property between tenancies.

What cover may respond?

Landlord Contents

Visitor Injury

A tenant damages furnishings beyond fair wear and tear.

What cover may respond?

Landlord Contents (Malicious Damage)

A man getting into a car outside an office building

Who needs landlord contents insurance?

If you supply anything inside the property, even just carpets, curtains and a cooker, buildings insurance won’t replace it. Most landlords own more than they realise.

This cover may be suitable for:

Landlords letting furnished property
Part-furnished lets with white goods
Landlords supplying carpets and curtains
Student let landlords
Landlords with several properties
Serviced and short-let owners

Not sure what counts as your contents?

Not sure what counts as your contents?

Carpets, curtains, white goods and light fittings are usually yours, even in an unfurnished let.

Carpets, curtains, white goods and light fittings are usually yours, even in an unfurnished let.

Pale curtains hanging beside a grey carpet in a bare room.

Cover built around what you provide

Cover built around what you provide

Landlord contents covers what you own inside the property, with accidental and malicious damage usually available as add-ons rather than included.

Landlord contents covers what you own inside the property, with accidental and malicious damage usually available as add-ons rather than included.

Landlord Contents

Landlord Contents

Covers furniture, white goods, carpets, curtains and light fittings you own.


Accidental Damage

Accidental Damage

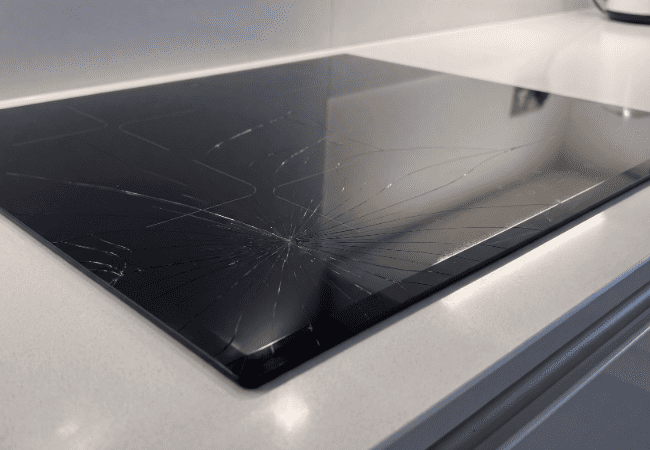
Optional cover for one-off accidents, a cracked hob, a torn sofa or a damaged worktop.


Malicious Damage by Tenants

Malicious Damage by Tenants

Covers deliberate damage by a tenant, which standard contents cover often excludes.


Buildings Insurance

Buildings Insurance

Covers the structure itself, fitted kitchens and bathrooms usually sit here, not under contents.


Property Owners’ Liability

Property Owners’ Liability

Protection if an item you supplied causes injury, such as a faulty appliance.


Loss of Rent

Loss of Rent

Helps replace income if contents damage makes the property unlettable while replacements are arranged.


Smiling bald man in a blue shirt standing with his arms folded outside a building.

Why choose us for landlord contents insurance?

We help you value what you actually own inside the property, so a claim isn’t reduced for underinsurance.

Specialist landlord insurers
Experienced UK advisers
Accidental and malicious damage options
Cover for furnished and part-furnished lets
Help setting the right contents sum insured
Portfolio cover for multiple properties

How the quote process works

How the quote process works

Getting landlord contents insurance takes four steps: tell us about the property, value what you provide, compare specialist insurers, then get covered, often the same day.

Getting landlord contents insurance takes four steps: tell us about the property, value what you provide, compare specialist insurers, then get covered, often the same day.

1

Tell us about the property

Whether it’s furnished, and what you supply.

2

Value your contents

Add up replacement cost, not what you originally paid.

3

We compare specialist insurers

We search our panel of specialist landlord insurers.

4

Get covered and get your documents

Receive your policy documents, usually the same day.

We're with you all the way

UK-based specialist advisers
Access to specialist insurers
No obligation, just expert help

Does your tenant know they need their own cover?

Does your tenant know they need their own cover?

Your contents policy covers what you provide, not their possessions. Saying so in writing at the start of a tenancy avoids disputes later.

Your contents policy covers what you provide, not their possessions. Saying so in writing at the start of a tenancy avoids disputes later.

Smiling woman carrying a box of belongings into a house while two others follow.

Trusted by thousands of businesses across the UK

Trusted by thousands of businesses across the UK

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

Landlord contents insurance guides

Landlord contents insurance guides

Practical advice on what to insure, valuing contents and tenant damage.

Practical advice on what to insure, valuing contents and tenant damage.

Does the Renters’ Rights Bill Change Your Landlord Insurance?

Does the Renters’ Rights Bill Change Your Landlord Insurance?

The Renters’ Rights Act introduces some of the biggest changes to England’s private rented sector in decades. From the removal of Section 21 ‘no fault’ evictions to changes in tenancy agreements and rent increases, landlords now face a different legal landscape than they did just a few years ago.

Read More
How to Reduce Your Landlord Insurance Premiums

How to Reduce Your Landlord Insurance Premiums

Landlord insurance is a vital cost for protecting your rental property, but that doesn’t mean you should overpay. This guide explains how to reasonably reduce your landlord insurance premiums while still protecting your investment.

Read More
Top Landlord Insurance Claims And How To Prevent Them

Top Landlord Insurance Claims And How To Prevent Them

Most landlord insurance claims follow familiar patterns. But the emerging pattern in 2025-26 is how often they happen and how much they cost. Rising repair prices and more extreme weather mean even routine claims are becoming more expensive.

Read More
Landlord Insurance UK: What Every Buy-to-Let Owner Needs to Know

Landlord Insurance UK: What Every Buy-to-Let Owner Needs to Know

Owning a buy-to-let property can offer a reliable income stream, but it also brings exposure to risks that standard home insurance may not cover. From accidental damage to liability claims and tenant-related losses, landlords face a unique set of challenges. Landlord insurance can provide tailored protection to help safeguard rental income, the property itself, and the landlord’s legal responsibilities.

Read More
Landlord Insurance Claims: What to Do When Tenants Cause Damage or Rent Goes Unpaid

Landlord Insurance Claims: What to Do When Tenants Cause Damage or Rent Goes Unpaid

Letting a property can bring consistent returns, but it can also come with unexpected challenges. From physical damage caused by tenants to rent arrears that disrupt income, landlords may face situations that require a carefully managed insurance claim.

Read More
Why Hidden Risks Can Cost Landlords Thousands

Why Hidden Risks Can Cost Landlords Thousands

Many landlords think they are covered because they hold a general business or property policy. But commercial property insurance is designed to address the real threats landlords face. Without it, one event can lead to huge losses.

Read More
Landlord Insurance Mistakes: 5 Things UK Property Owners Get Wrong

Landlord Insurance Mistakes: 5 Things UK Property Owners Get Wrong

When arranging residential landlord insurance in the UK, it can be easy to assume standard policies cover everything. However, there are several common mistakes property owners make when choosing or reviewing their level of cover. Overlooking these could leave landlords exposed to financial risks.

Read More
What Commercial Landlord Insurance Actually Covers: From Fires to Tenant Lawsuits

What Commercial Landlord Insurance Actually Covers: From Fires to Tenant Lawsuits

When owning a commercial property, arranging the right commercial landlord insurance can help protect both the building and your business interests. While many property owners understand the basics, not everyone knows exactly what this type of cover includes. From fire damage to legal actions linked to tenants, commercial landlord insurance could offer vital financial protection.

Read More
Do You Need Landlord Insurance If Your Tenant Already Has Business Insurance?

Do You Need Landlord Insurance If Your Tenant Already Has Business Insurance?

When letting out a commercial property, some landlords assume that if a tenant holds business insurance, it covers all risks. In reality, commercial landlord insurance and tenant business insurance serve different purposes. Knowing where the responsibilities lie helps property owners avoid gaps in financial protection.

Read More

Landlord contents insurance FAQs

Landlord contents insurance FAQs

Straight answers on what’s covered, tenant damage and cost.

Straight answers on what’s covered, tenant damage and cost.

It covers items you own inside a rental property, white goods, carpets, curtains, light fittings and any furniture you supply. Buildings insurance covers the structure; this covers what sits inside it.

Still have questions?

Our advisers are here to help you find the right solution.