
HomeBusiness InsuranceTakeaway Insurance

TakeawayInsurance

Takeaway Insurance

Public liability, product liability and employers’ liability cover built for takeaways and fast food businesses.

Public liability, product liability and employers’ liability cover built for takeaways and fast food businesses.

Kitchen equipment
Delivery drivers
Allergen claims
Compare from 20+ Trusted Insurers

Cover for takeaways across the UK

Speak to a specialist 0330 027 0996

Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL
Allianz
Granite Underwriting
Inshur
Aviva
Jensten Insurance Brokers
ERS
Bond Lovis
QBE
Victor
Admiral business
Axa
Highway
Collingwood
Zurich
KGM
Ageas
NIG
Sabre
DCL

What is takeaway insurance?

Takeaway insurance is a combination of covers built around preparing and serving food to go, public liability for customer injury, product liability for the food you serve, and employers’ liability if you have staff.

Fryers, grills and late-night trading all bring their own risks. Standard cover needs to reflect how a takeaway actually operates, not just a smaller version of a restaurant.

Takeaway insurance can include:

Public liability
Employers’ liability
Product liability
Business contents & stock
Late-night trading cover
Business van insurance (separate policy)
A man getting into a car outside an office building

Cover often bought alongside takeaway insurance

Public Liability

Public Liability

Covers claims if your business injures a customer or damages their property.

Explore Cover
Employers’ Liability

Employers’ Liability

A legal requirement once you employ any staff, even casual help.

Explore Cover
Product Liability

Product Liability

Covers claims that food you’ve served caused illness or a reaction.

Explore Cover
Business Contents

Business Contents

Protects kitchen equipment, stock and fixtures.

Explore Cover
Tools & Equipment

Tools & Equipment

Covers kitchen equipment against breakdown and damage.

Explore Cover

Deep fat fryers or open flame cooking?

Deep fat fryers or open flame cooking?

Fire risk from cooking equipment is one of the biggest claims takeaways face. Make sure your cover reflects it.

Fire risk from cooking equipment is one of the biggest claims takeaways face. Make sure your cover reflects it.

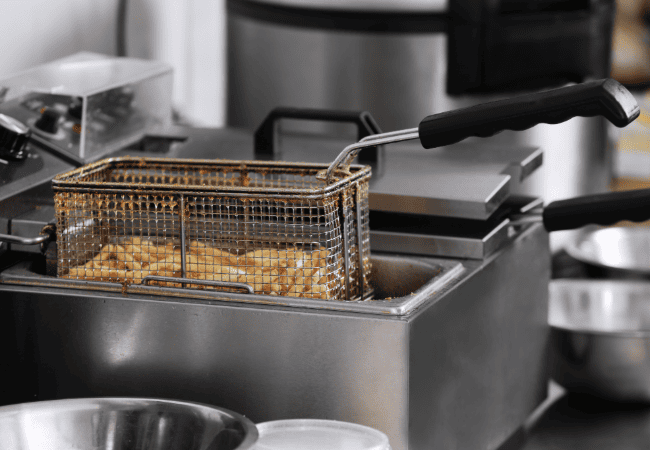
Commercial deep fat fryer with baskets of food.

Are your delivery drivers covered?

Are your delivery drivers covered?

It depends who’s doing the delivering, your own staff or a third-party platform.

It depends who’s doing the delivering, your own staff or a third-party platform.

SituationYour responsibilityWho’s covered

You employ your own delivery drivers

Yes, employers’ liability applies

You need employers’ liability for them

A driver uses their own car for deliveries

Yes, check their own insurance covers business use

Their personal car insurance may not cover business deliveries

You use a platform like Uber Eats or Deliveroo

Usually not, the platform is responsible

The platform’s own insurance typically applies

A customer’s order is damaged in transit

Check your policy for goods in transit cover

Not automatically included in standard cover

Top Tip

If a delivery driver uses their own car for your business, check they have business use cover, a standard personal car policy usually doesn’t include it.

How much does takeaway insurance cost?

There’s no fixed price. It depends on your cooking equipment, whether you deliver, your trading hours and your claims history.

Cooking equipment

Deep fat fryers and grills carry more fire risk than lighter food prep.

Trading hours

Late-night trading can affect your risk profile.

Number of staff

More employees increase your employers’ liability exposure.

Level of cover

Adding product liability or a higher limit increases your premium.

Delivery method

Own drivers, third-party platforms or collection-only all carry different risk.

Claims history

A clean claims record helps keep premiums down at renewal.

Chef in whites giving a thumbs up in a kebab shop kitchen.

Why choose Insurance Revolution for takeaway insurance?

We make sure your cover reflects fryers, late trading and deliveries, not just a scaled-down restaurant policy.

Access to 20+ UK insurers
Cover for fire and cooking equipment
Late-night trading options
Experienced UK-based advisers
Help with delivery driver cover
Human support when you claim

How to get takeaway insurance

How to get takeaway insurance

Getting takeaway insurance takes four steps: tell us about your business, choose your covers, compare specialist insurers, then get covered, often the same day.

Getting takeaway insurance takes four steps: tell us about your business, choose your covers, compare specialist insurers, then get covered, often the same day.

1

Tell us about your business

Your equipment, trading hours and whether you deliver.

2

Choose your covers

Public liability, product liability and any extras.

3

We compare specialist insurers

We search our panel of 20+ UK insurers.

4

Get covered and trading

Receive your documents, usually the same day.

We’re with you all the way

UK-based specialist advisers
Access to specialist insurers
No obligation, just expert help

Delivering through Uber Eats or Deliveroo?

Delivering through Uber Eats or Deliveroo?

Third-party platforms usually cover their own drivers, but check where your responsibility starts and ends.

Third-party platforms usually cover their own drivers, but check where your responsibility starts and ends.

Smiling delivery driver in a car reaching for a large yellow insulated bag on the passenger seat.

Trusted by thousands of businesses across the UK

Trusted by thousands of businesses across the UK

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.

Takeaway insurance guides

Takeaway insurance guides

Delivery drivers, hot oil and allergen labelling on takeaway orders.

Delivery drivers, hot oil and allergen labelling on takeaway orders.

Does Takeaway Insurance Cover Food Poisoning, Burns & More? Our Guide

Does Takeaway Insurance Cover Food Poisoning, Burns & More? Our Guide

Running a takeaway or fast food business in the UK can involve managing a fast-paced environment where accidents and food safety risks may arise. From customer slips in the waiting area to food poisoning claims linked to allergens or contamination, unexpected incidents can happen despite robust safety procedures.

Read More
Top 7 Takeaway Insurance Extras: Equipment Breakdown & More

Top 7 Takeaway Insurance Extras: Equipment Breakdown & More

Running a takeaway or fast food business in the UK can bring unique risks that extend beyond basic insurance policies. While core covers such as buildings, contents, and employers’ liability may form the foundation of many insurance packages, there are several additional protections that could be valuable for takeaway operators.

Read More

Takeaway insurance FAQs

Takeaway insurance FAQs

Straight answers on cover, deliveries, fire risk and cost.

Straight answers on cover, deliveries, fire risk and cost.

Takeaway insurance is a combination of covers built around preparing and serving food to go: public liability for customer injury, product liability for the food you serve, and employers’ liability if you have staff.

Still have questions?

Our advisers are here to help you find the right solution.