
How much stock cover do you need?
Setting a sum insured that holds up at your busiest point.

Cover for the goods you hold to sell, against theft, fire, flood and spoilage, at the value it would cost to replace them.
Cover for the goods you hold to sell, against theft, fire, flood and spoilage, at the value it would cost to replace them.
 Theft, fire or floodSeasonal stock peaksSpoilage after breakdown
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
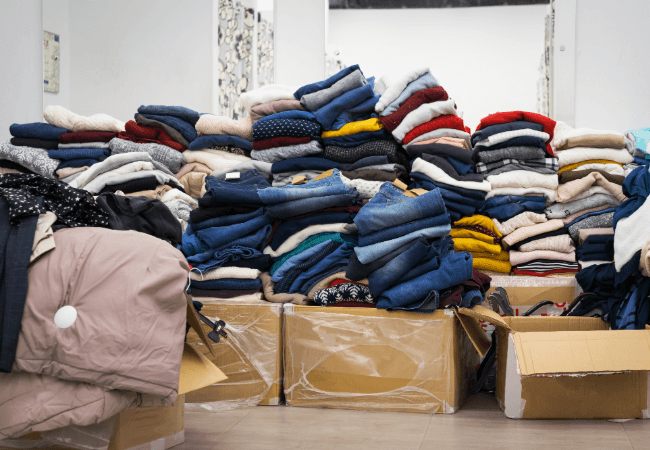
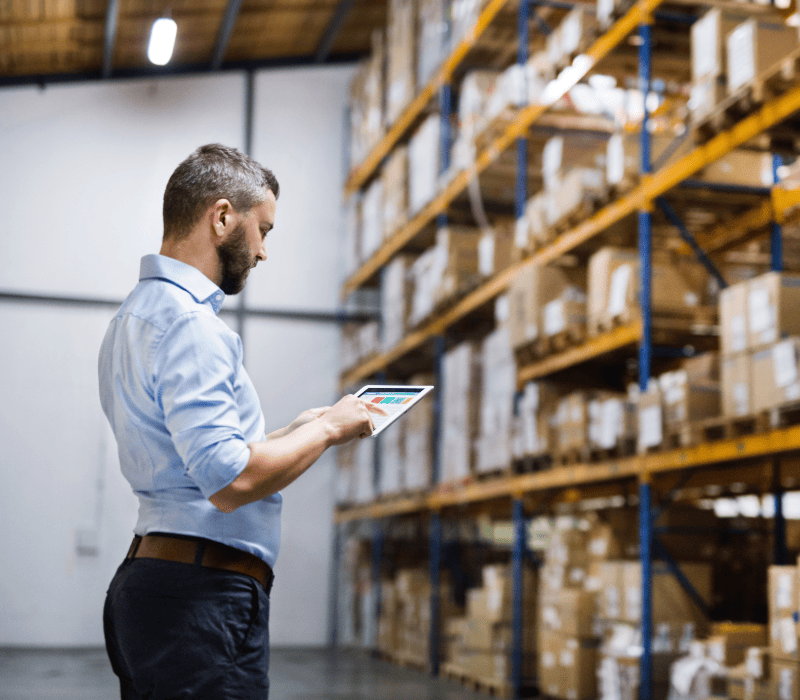
Stock insurance covers the goods you hold to sell, along with raw materials and work in progress, against theft, fire, flood and accidental damage at your premises.
It sits alongside business contents rather than inside it: contents covers your fixtures, fittings and equipment, while stock covers the goods that pass through your hands.
Stock insurance can include:
 Theft after forced entryEscape of waterDeterioration after breakdownFire and smoke damageAccidental damageSeasonal increases
Any business whose money is tied up in goods on a shelf, in a cellar or in a warehouse. If a break-in or a burst pipe would leave you with nothing to sell, your stock needs its own sum insured.
You should seriously consider cover if you:
Hold bulk stock in a warehouseCarry high-value or small itemsBuild to order from raw materialsSell goods from a shop floorStore perishables or chilled goodsTake stock on sale-or-returnEnough to replace your stock at cost price, at the point in the year when you are holding the most. Insuring an average figure is the single most common mistake, because losses rarely happen in a quiet month.
Most policies let you declare a seasonal increase for an agreed period, so a retailer buying in for Christmas or a garden centre stocking up for spring is not left underinsured when it matters.
Work out your sum insured from:
Stock at cost, not retail priceGoods held on consignmentWork in progressYour highest point in the yearRaw materials and packaging
Where stock cover ends and another policy begins
Where stock cover ends and another policy begins
Stock is covered while it sits at your premises. Once it moves, or once it belongs to someone else, a different policy usually answers, which is where most claims come unstuck.
Stock is covered while it sits at your premises. Once it moves, or once it belongs to someone else, a different policy usually answers, which is where most claims come unstuck.
| Where the stock is | Usually insured by | What to know |
|---|---|---|
On your premises | Your stock policy | Theft needs forcible entry on most wordings |
Being delivered or moved | Goods in transit cover | Stock cover stops at your door |
In a third-party warehouse | Your stock policy, if declared | Off-site storage has to be named on the policy |
Held on sale-or-return | You, often as bailee | You can be responsible for goods you don’t own |

Top Tip
Tell your insurer how you hold stock, not just what it is worth. Consignment and sale-or-return terms can make you responsible for goods that still belong to your supplier.
What could go wrong with your stock?
What could go wrong with your stock?
Most stock claims come from a break-in, water finding its way into a stockroom, or a fridge failing overnight and taking everything in it.
Most stock claims come from a break-in, water finding its way into a stockroom, or a fridge failing overnight and taking everything in it.
Once you’re covered we’ll send your documents the same day. Your schedule is where the stock figures live, so it’s worth reading rather than filing.
If you employ anyone, your employers’ liability certificate must be displayed where staff can see it.
Your schedule typically shows:
Your stock sum insuredSingle-article limitsNamed storage locationsAny seasonal increase agreedSecurity conditions you must meet
Cover often bought alongside stock insurance
Cover often bought alongside stock insurance
Stock is rarely insured on its own. Most businesses hold public liability alongside it, and add business interruption so a loss of stock doesn’t also mean weeks of lost trade.
Stock is rarely insured on its own. Most businesses hold public liability alongside it, and add business interruption so a loss of stock doesn’t also mean weeks of lost trade.
 Recommended
Business Contents
Covers fixtures, fittings and equipment, the things stock sits on.
 Recommended
Public Liability
Covers injury or damage claims from customers and visitors.
 Optional
Business Interruption
Replaces income lost while you have nothing to sell.
 Optional
Goods in Transit
Covers stock while it’s being delivered or moved between sites.
 Optional
Employers’ Liability
A legal requirement once you employ any staff, even casual help.
 Popular
Commercial Combined
Bundle public liability with your other covers into one policy and one renewal date.
There’s no fixed price. Your sum insured is the main driver, along with what the stock is, how attractive it is to a thief and how well the building is protected.
Your stock sum insured
The peak value you hold, at cost price rather than what you sell it for.
Claims history
A clean claims record helps keep premiums down at renewal.

Security at the premises
Locks, shutters, alarms and whether the alarm is monitored all count.

What the stock actually is
Alcohol, tobacco, electronics and jewellery cost more to cover than bulky low-value goods.

Claims history
A clean record keeps your premium down at renewal.

Where it’s kept
A locked stockroom reads differently to an open yard or a shared unit.
How to get stock insurance
How to get stock insurance
Getting stock insurance takes four steps: tell us what you sell, value your stock at its peak, compare insurers, and get covered, often the same day.
Getting stock insurance takes four steps: tell us what you sell, value your stock at its peak, compare insurers, and get covered, often the same day.

Tell us what you sell
What you hold, where you hold it and how the building is secured.

Value your stock
Your peak stock value at cost, plus anything held on consignment.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and get your documents
Receive your documents, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Stock insurance guides
Stock insurance guides
Practical advice on valuing your stock and claiming when it goes.
Practical advice on valuing your stock and claiming when it goes.
Stock insurance FAQs
Stock insurance FAQs
Straight answers on sums insured, theft conditions and spoilage.
Straight answers on sums insured, theft conditions and spoilage.
Stock insurance covers the goods you hold to sell, plus raw materials and work in progress, against theft, fire, flood and accidental damage while they are at your premises.
Still have questions?
Our advisers are here to help you find the right solution.