



What happens to your income if you’re injured?
Why the self-employed have no sick pay to fall back on.

Pays a cash benefit if an injury stops you working, cover for you, your directors or the people on your payroll.
Pays a cash benefit if an injury stops you working, cover for you, your directors or the people on your payroll.
 Weekly benefitPermanent injuryNo sick pay behind you
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
Personal accident insurance pays a cash benefit if an injury leaves you unable to work. It covers the gap left when you are self-employed and there is no employer sick pay behind you.
Benefits are paid directly to you or the business rather than to a third party, and you choose how the money is used, rent, wages, cover for your work or household bills.
Personal accident insurance can include:
 Weekly benefit while injuredPermanent disabilityLoss of limb or sightDeath benefitHospital stay benefitBroken bones cover
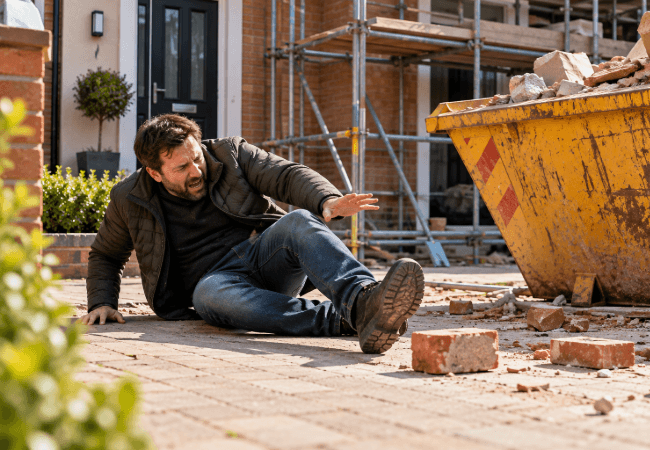
Anyone whose income stops when they do. It matters most to sole traders and directors, and to employers who want to offer cover to a team doing physical work.
You should seriously consider cover if you:
Have no employer sick payRun a business that needs you presentEmploy staff doing manual workWork for yourselfDo physically demanding workHave a mortgage or rent to meetIf you are self-employed, nothing arrives automatically. Statutory Sick Pay is only available to employees, so a sole trader or director who cannot work usually has no income at all until they are back on the job.
Personal accident cover is designed for that gap. It pays an agreed weekly amount while you are unable to work, so the business and the household keep running.
It typically pays out for:
Temporary total disabilityLoss of a limb or sightSpecified broken bonesPermanent total disabilityHospital admission
Who gets paid, and when?
Who gets paid, and when?
Benefits are set when you take the policy out, so you know in advance what would be paid and how long for.
Benefits are set when you take the policy out, so you know in advance what would be paid and how long for.
| What happens | Who receives it | What to know |
|---|---|---|
You can’t work for a time | You | Paid weekly after the deferral period you choose |
A permanent injury | You | A one-off lump sum set when you take the policy |
A key employee is injured | Your business | Can be arranged to pay the business instead |
Accidental death | Your estate | Paid as a lump sum to those you leave behind |

Top Tip
Check the deferral period before you buy. A shorter wait before benefits start costs more, but a long deferral can leave you without income for exactly the weeks it hurts most.
What could stop you working?
What could stop you working?
Most personal accident claims come from falls, lifting injuries, hand and power tool accidents, or a road incident on the way to a job.
Most personal accident claims come from falls, lifting injuries, hand and power tool accidents, or a road incident on the way to a job.
Once you’re covered we’ll send your documents the same day. It’s worth keeping your schedule somewhere your family can find it, since a claim may be made when you cannot make it yourself.
If you employ anyone, your employers’ liability certificate must be displayed where staff can see it.
Your certificate typically shows:
Your business nameYour insurer’s namePolicy numberPolicy start and renewal datesYour deferral period
Cover often bought alongside personal accident insurance
Cover often bought alongside personal accident insurance
Personal accident protects your income. Most sole traders and directors hold liability cover alongside it, and add tools cover depending on the business.
Personal accident protects your income. Most sole traders and directors hold liability cover alongside it, and add tools cover depending on the business.
 Recommended
Public Liability
Covers injury or damage you cause to someone else or their property.
 Recommended
Sole Trader Insurance
A package built around working for yourself rather than a company.
 Optional
Tools Insurance
Covers your tools against theft from the van, site or workshop.
 Optional
Business Interruption Insurance
Covers lost income and ongoing costs if the business itself has to stop trading.
 Optional
Employers’ Liability
A legal requirement once you employ anyone, including casual staff.
 Popular
Commercial Combined
Bundle public liability with your other covers into one policy and one renewal date.
There’s no fixed price. The benefit you choose and your occupation are the main drivers, along with how long you’re willing to wait before payments start.
The benefit you choose
A higher weekly benefit and a larger lump sum both raise the premium.
Claims history
A clean claims record helps keep premiums down at renewal.
Your deferral period
Waiting longer before benefits begin brings the cost down.

Your occupation
Manual and at-height trades are priced higher than office-based work.
Your age
Premiums usually rise with age, as claim likelihood increases.
Who is covered
Covering a whole team costs more than covering one person.
How to get personal accident insurance
How to get personal accident insurance
Getting personal accident cover takes four steps: tell us about your work, choose your benefit, compare specialist insurers, and get covered, often the same day.
Getting personal accident cover takes four steps: tell us about your work, choose your benefit, compare specialist insurers, and get covered, often the same day.

Tell us about your work
What you do day to day and who needs to be covered.

Choose your benefit
Your weekly benefit, lump sum and deferral period.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and get your documents
Receive your certificates, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Personal accident insurance guides
Personal accident insurance guides
Practical advice on benefits, deferral periods and claiming.
Practical advice on benefits, deferral periods and claiming.
What happens to your income if you’re injured?
Why the self-employed have no sick pay to fall back on.
How to choose your weekly benefit
Matching your benefit to what you actually need to cover.
Personal accident or income protection?
How the two differ, and when each one fits.
Personal accident insurance FAQs
Personal accident insurance FAQs
Straight answers on benefits, waiting periods and who gets paid.
Straight answers on benefits, waiting periods and who gets paid.
Personal accident insurance pays a cash benefit if an injury leaves you unable to work. It covers the gap left when you are self-employed and have no employer sick pay behind you.
Still have questions?
Our advisers are here to help you find the right solution.